


Brent Crude Oil and West Texas Intermediate (WTI) are the world’s two primary oil price benchmarks.
WTI is the main reference price for North American crude while Brent Crude, produced from the North Sea, is seaborne and used to price around two‑thirds of globally traded oil.
Because Brent reflects internationally traded supply, it is the relevant benchmark for countries such as Australia that rely heavily on imported refined fuels.
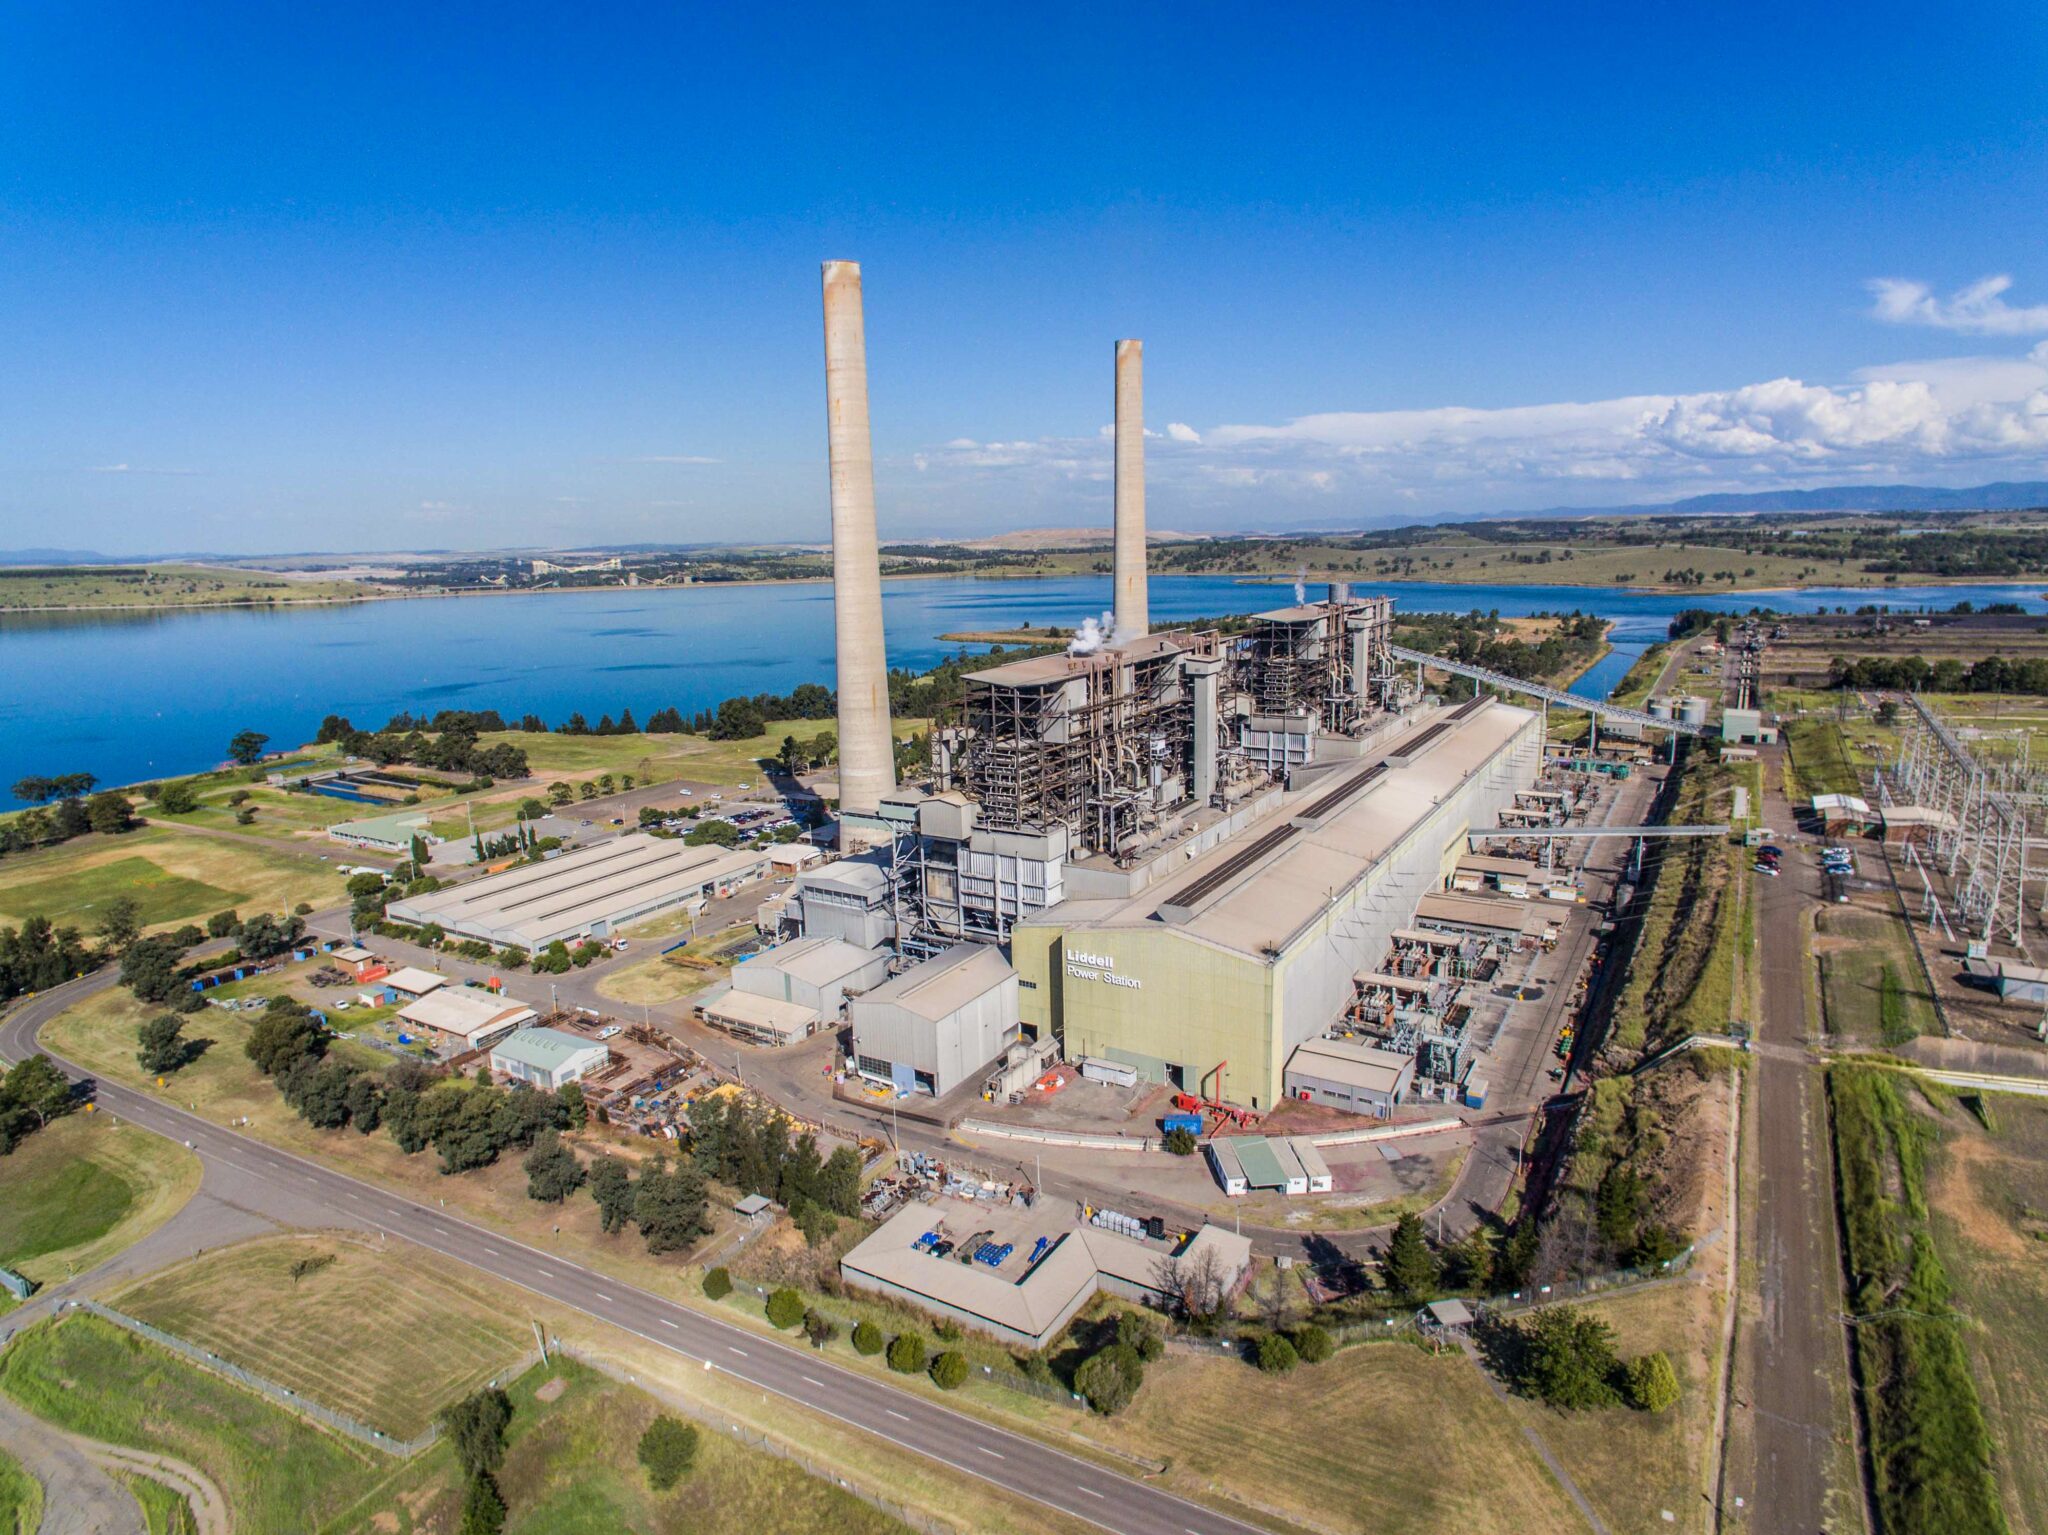
In the 2026 oil crisis, driven largely by geopolitical conflict and disruption risks through key shipping routes such as the Strait of Hormuz, Brent Crude has traded at higher process per barrel. In Australia, domestic fuel prices follow Brent linked refined product markets rather than US oil trends.
As a result, global oil shocks transmit quickly and directly into Australian fuel costs.

"The current Brent driven oil shock represents a clear risk to Australian inflation and by extension, to property discount rates and capitalisation rates." - Greg Preston AM
Near‑Term Inflationary Impacts in Australia
Automotive fuel represents approximately 3-4 per cent of the Australian CPI basket, but its volatility gives it an outsized influence on short term inflation outcomes. Recent commentary from economists and banks notes that Australia’s inflation was already running above the Reserve Bank of Australia’s (RBA) target band before the latest oil shock, increasing the risk that higher fuel prices now reinforce, rather than briefly interrupt, the disinflationary trend.
A sustained rise in Brent linked fuel prices is expected to lift headline CPI in the near term, with second round impacts extending into transport, logistics, construction and consumer goods if elevated energy costs persist beyond one or two quarters.
Banks have warned that, in this environment, inflation pressures may remain broader based and more persistent than previously anticipated.
Implications for Interest Rates and Monetary Policy
From a policy perspective, the RBA typically “looks through” initial fuel price volatility. However, current conditions are different. The combination of strong domestic demand and externally driven energy costs has increased the risk that inflation expectations become entrenched. Recent analysis highlights that oil prices above historical norms complicate the RBA’s task and materially increase the probability of a “higher for longer” interest rate environment.
Potential Consequences for Property and Capital Markets
For property and real asset markets, energy driven inflation has indirect but meaningful consequences.
Persistently higher inflation places upward pressure on bond yields and discount rates, particularly for long duration assets such as office and infrastructure style investments.
Conversely, assets with inflation linked income, strong pricing power or shorter lease structures including retail and parts of the industrial and logistics sectors are relatively better positioned.
Construction and development activity faces additional pressure as higher fuel and freight costs flow through to materials and labour, tightening feasibility margins. At the same time, energy and energy linked infrastructure assets may benefit from elevated prices and increased trading volumes driven by market volatility.
Outlook and Risk
In summary, the current geopolitical conflict driven oil shock represents a clear risk to Australian inflation. While initially concentrated in fuel, the broader risk lies in persistence and pass through.
For investors, valuers and decision makers, this reinforces the need for conservative inflation assumptions, careful discount rate selection and close monitoring of second round effects across the economy.
Asset Class Implications
Office Property
Office assets are among the most exposed to inflation driven increases in discount rates. Longer lease terms, slower rental growth and structural occupancy challenges mean income is less flexible in offsetting higher required returns.
Elevated energy costs also affect building operating expenses, particularly for older stock. As a result, cap rate expansion risk remains most pronounced in the office sector, especially for secondary and non prime assets.
Retail Property
Retail outcomes are more nuanced. Prime retail assets with essential services and non discretionary expenditure exposure and inflation indexed leases are relatively defensive, as rent reviews provide partial protection against rising costs.
Conversely, discretionary retail faces pressure from reduced consumer spending power as fuel and household costs rise. Cap rates are likely to remain bifurcated, with well located neighbourhood and convenience retail outperforming larger discretionary focused centres.
Industrial Property
Industrial property is comparatively well positioned. Strong tenant demand, shorter lease terms and CPI linked rental structures provide a buffer against inflation. While higher transport and fuel costs affect occupiers, they also reinforce the value of well located logistics facilities closer to end consumers. Industrial cap rates are likely to remain the most resilient, notwithstanding modest upward pressure in a higher rate environment.
Hotel and Tourism Property
Hotels and tourism assets are likely to experience a mixed impact. Higher fuel costs can dampen discretionary travel, particularly domestic travel, yet inflation can support room rate growth during periods of strong demand. Operating costs, especially energy, rise materially in this environment, increasing earnings volatility.
As a result, investors are likely to apply higher discount rates to reflect cash flow risk, particularly for leisure dependent assets.
Our Team of qualified valuers, researchers and advisers bring a wealth of knowledge and experience to the table.
Gregory Preston AM
Investment Valuation and Capital Market Advisory
B.Comm., MAppFin, Ass. Dip. Val., LFAPI, FRICS, GAICD
Chair & Managing Director
Gregory Rowe
Real Estate, Asset, Plant & Machinery Valuation
B.Bus., FAPI, CPV, CPV P&M
Chair & Managing Director
Sunny Gao
Finance & Operations
B.Acc
Manager
Richard Lawrie
Investment Valuation & Capital Markets Advisory
BAppSc (Land Econ), FAPI, MRICS, CPV
Director
Dimity Lee
Investment Valuation and Capital Market Advisory
B.Prop. & Sus. Dev. (Val), AAPI, CPV
Associate Director
Daniel Saliba
Investment Valuation and Capital Market Advisory
B.Prop.Econ. (Hons), AAPI, CPV
Associate Director
Abby Doran
Marketing
B.Bus.Man.Mktg (Hons)
Executive Assistant to Greg Preston AM and Marketing Coordinator
Neil Watson
Investment Valuation and Capital Market Advisory
B.PropVal, GradCertAppFin, AAPI, CPV
Associate Director
Ramina Ravivaratharajah
Finance & Operations
BCom MFin Macq.
Finance & Operations Accountant
David Gould
Commercial & Residential Property Management Services
B.Bus & Comm.,Prop. AAPI, RPV
Commercial Property Manager
Joshua Naumoff
Investment Valuation and Capital Market Advisory
B.Bus & Comm.,Prop. AAPI, CPV
Associate Director
Anthony Antinora
Residential Property Valuations Services
B.Bus & Comm.,Prop. AAPI, CPV
Team Leader & Manager

Insights
19/02/26
Economic Snapshot January 2026

Insights
22/02/26
Transactions in Review January 2026

Insights
10/03/26
Economic Snapshot February 2026
Insights
15/03/26
Transactions in Review February 2026

Insights
21/04/26
Economic Snapshot March 2026
Insights
05/04/26
Transactions in Review March 2026
Insights
26/05/26
Economic Snapshot April 2026
Insights
01/06/26
Economic Snapshot May 2026

Insights
05/01/26
Economic Snapshot December 2025

Insights
09/12/25
Transactions in Review November 2025

Insights
06/12/25
Economic Snapshot November 2025

Insights
01/11/25
Transactions in Review October 2025

Insights
01/11/25
Economic Snapshot October 2025

Insights
01/10/25
Transactions in Review September 2025

Insights
01/10/25
Economic Snapshot September 2025

Insights
01/09/25
Transactions in Review August 2025

Insights
01/09/25
Economic Snapshot August 2025

Insights
05/08/25
Transactions in Review July 2025

Insights
01/08/25
Economic Snapshot July 2025

Insights
05/07/25
Transactions in Review June 2025

Insights
01/07/25
Economic Snapshot June 2025

Insights
29/06/25
Transactions in Review May 2025

Insights
01/06/25
Economic Snapshot May 2025

Insights
03/05/25
Economic Snapshot April 2025

Insights
10/05/25
Transactions in Review April 2025

Insights
23/04/25