


Preston Rowe Paterson undertake development valuations and provide valuation advice for all asset classes including but not limited to commercial, retail, industrial, accommodation hotels, data warehouses, build to sell and build to rent residential and special purpose asset classes
Our valuations are often required for site acquisition purposes and debt funding. We also undertake highest and best use analysis and studies and assist clients consider asset repurposing options for assets which are drawing near to the end of economic useful lives. This has been the case in certain classes of office accommodation where the work from home conundrum has impacted office demand.

'Development real estate demands more than a point in time valuation. Preston Rowe Paterson delivers considered advice that reflects feasibility, risk and future potential' - Gregory Preston AM
Our forward thinking approach
We regularly assist clients at varying stages of the development cycle such as pre and post development consent.
Our valuation team is well versed in the valuation approaches which include direct comparison and land value residuals and feasibility studies.
Understanding the land development site markets as well as markets for values as if complete (gross realisations) based on leasing and investment sales evidence is paramount. Using residual land value (feasibility study) approaches to hone values with a range suggested by comparable sales has always the approach of Preston Rowe Paterson.
It enables a deeper understanding of the issues impacting the value of the property and the sensitivity of inputs to an approach which is essential to understand development risk.
The task of understanding a development’s value as if complete and residual land value is best considered by comprehensive feasibility study to compliment comparable sales
Discounted Cash Flow (DCF) methodologies, whether undertaken on a nominal basis (with growth) or a static basis (without growth), integrate the full range of valuation analysis and assumptions.
At Preston Rowe Paterson, we apply our own proprietary DCF models alongside established off‑the‑shelf solutions such as Estate Master, all of which can be configured to adopt nominal or real cash flows. A detailed understanding of each input is critical to producing robust and reliable valuation advice.
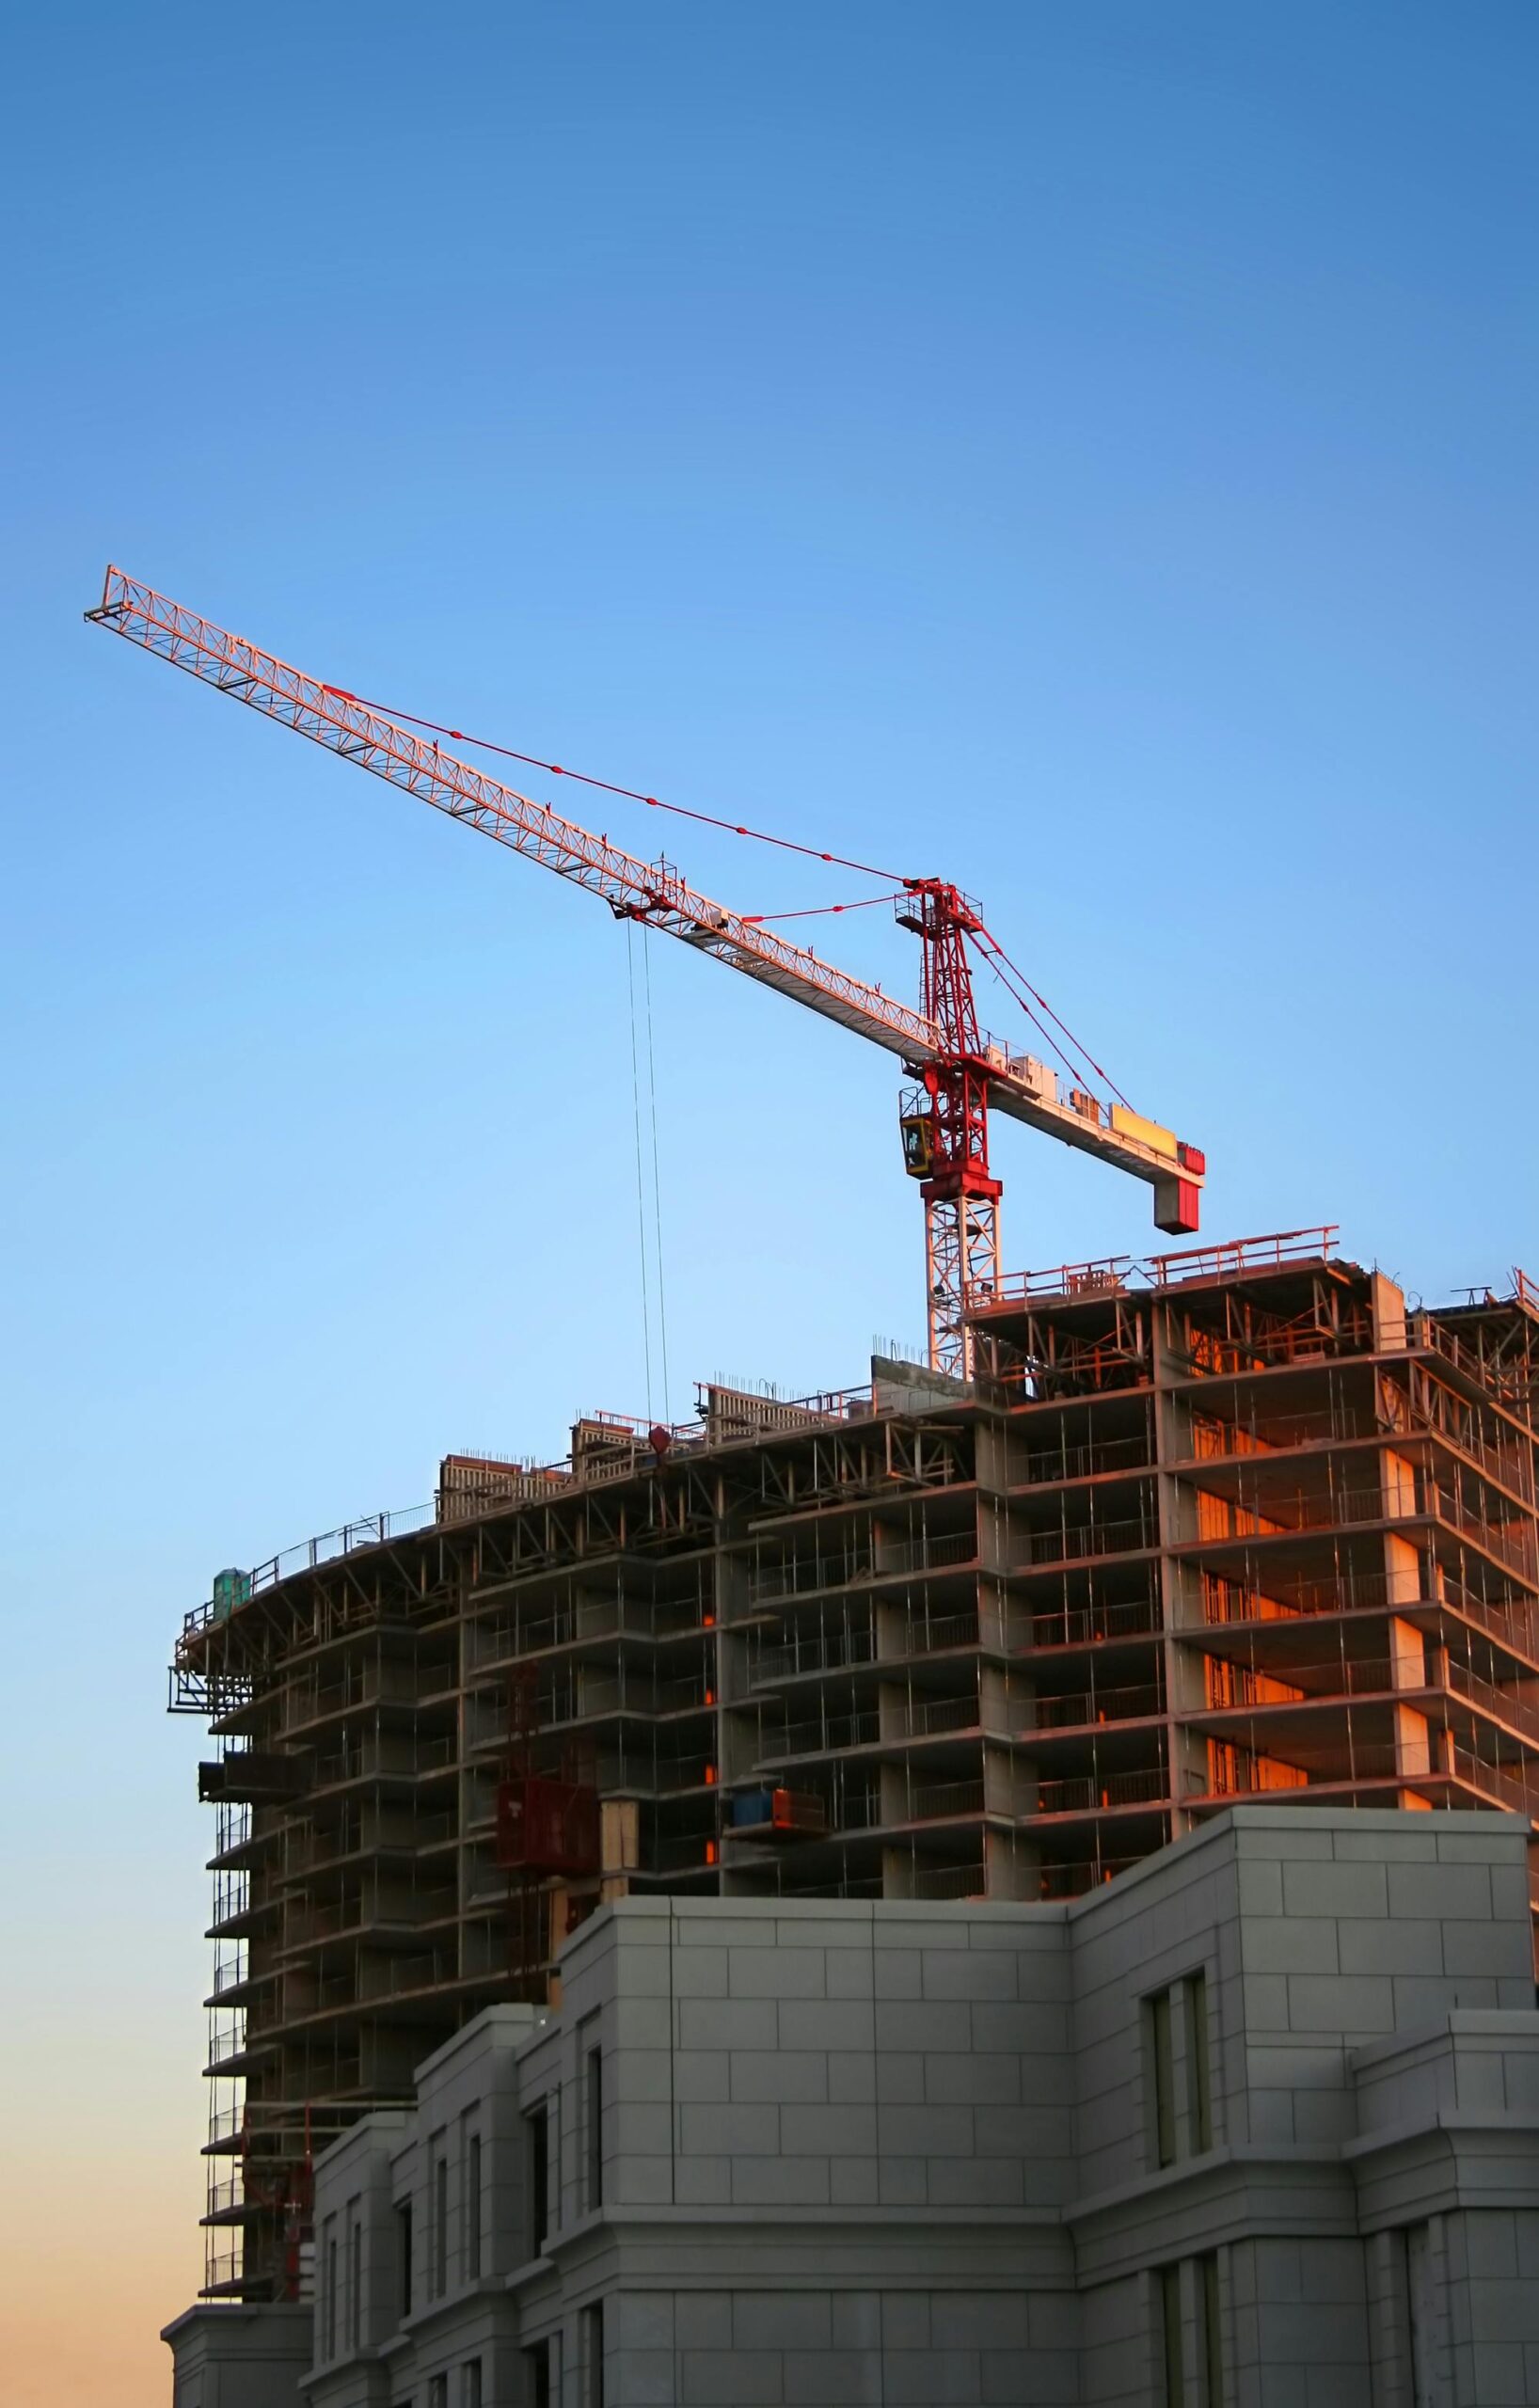
Our clients seek our development valuation and advisory services for a multitude of reasons including:-
- Acquisitions & disposals;
- Alternative use as well as highest & best use analysis;
- Compulsory acquisition & resumption;
- Feasibility studies;
- Litigation support;
- Marketing & development strategies;
- Mortgage valuations;
- Rating & taxing objections;
- Receivership, insolvency & liquidation valuations & support/advice; and
- Sensitivity analysis
Development Valuation Models
The inputs to any development valuation model which isolates profit or return consider:-
- The land price;
- Transfer (stamp) duty;
- Holding charges during the development and sell period (rates and taxes);
- Up front funding costs;
- State and local development contributions;
- Voluntary Planning Agreement (VPA) costs and offsets;
- Construction costs;
- Cost drawdowns (S curves)
- Cost growth during the development and sell period (nominal cash flows);
- Design and project management fees;
- As if complete sale values;
- Agents fees and legal fees on sale;
- GST on site acquisition;
- GST during construction;
- GST on sale and margin scheme;
- Debt funding cost; and
- Equity funding cost.

Our Team of qualified valuers, researchers and advisers bring a wealth of knowledge and experience to the table to assist with development valuations, highest and best use studies and value maximising strategies for your development projects
Gregory Preston AM
Investment Valuation and Capital Market Advisory
B.Comm., MAppFin, Ass. Dip. Val., LFAPI, FRICS, GAICD
Chair & Managing Director
Gregory Rowe
Real Estate, Asset, Plant & Machinery Valuation
B.Bus., FAPI, CPV, CPV P&M
Chair & Managing Director
Sunny Gao
Finance & Operations
B.Acc
Manager
Richard Lawrie
Investment Valuation & Capital Markets Advisory
BAppSc (Land Econ), FAPI, MRICS, CPV
Director
Dimity Lee
Investment Valuation and Capital Market Advisory
B.Prop. & Sus. Dev. (Val), AAPI, CPV
Associate Director
Daniel Saliba
Investment Valuation and Capital Market Advisory
B.Prop.Econ. (Hons), AAPI, CPV
Associate Director
Abby Doran
Marketing
B.Bus.Man.Mktg (Hons)
Executive Assistant to Greg Preston AM and Marketing Coordinator
Neil Watson
Investment Valuation and Capital Market Advisory
B.PropVal, GradCertAppFin, AAPI, CPV
Associate Director
Ramina Ravivaratharajah
Finance & Operations
BCom MFin Macq.
Finance & Operations Accountant
David Gould
Commercial & Residential Property Management Services
B.Bus & Comm.,Prop. AAPI, RPV
Commercial Property Manager
Joshua Naumoff
Investment Valuation and Capital Market Advisory
B.Bus & Comm.,Prop. AAPI, CPV
Associate Director
Anthony Antinora
Residential Property Valuations Services
B.Bus & Comm.,Prop. AAPI, CPV
Team Leader & Manager